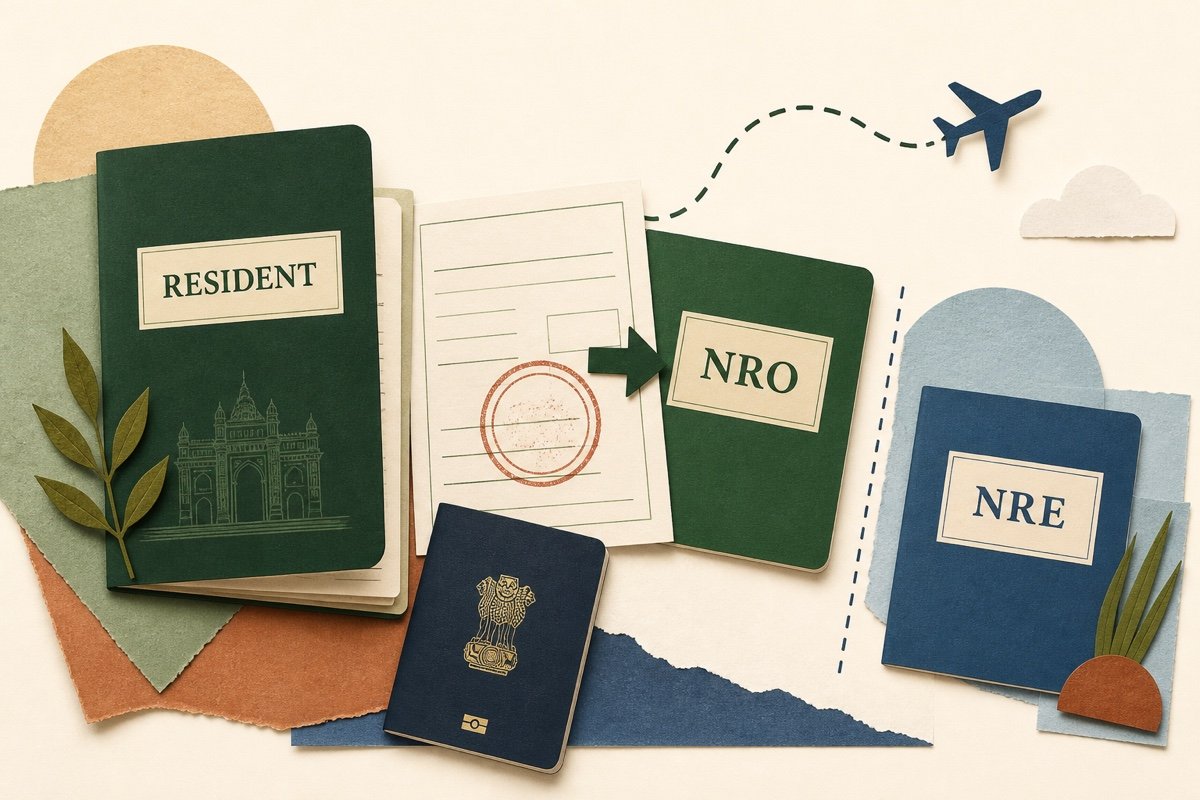
Moving abroad changes your banking status in India. The main thing to get right is the account redesignation step: your resident savings account should not keep running as a resident account once your status changes. In practice, that usually means converting it to an NRO account or closing it, while opening an NRE account separately if you have eligible foreign remittances to park in India.
If you want the account-type basics first, read A Simple Guide to NRE, NRO, and FCNR Accounts. If you are also thinking about sending money back abroad later, read NRI Repatriation Rules Made Simple.
Quick answer
When you become an NRI, the account should be redesignated or closed, not left as a resident account.
The old resident savings account is normally the account that becomes NRO.
An NRE account is opened separately for eligible foreign remittances and repatriable funds.
That is the short version. The rest of this guide explains the practical steps.
What changes after you move abroad?
RBI's current FAQ says that when a resident Indian becomes a person resident outside India, the existing resident account should be designated as NRO. The same FAQ says NRE accounts should be redesignated as resident accounts or moved to RFC accounts when someone becomes resident again later.
That is why many banks do not convert a resident savings account directly into NRE in one step.
NRO vs NRE in plain English
Non-Resident Ordinary accounts are used for money linked to India, such as rent, dividends, pension, interest, sale proceeds, and balances already held in India.
Non-Resident External accounts are used for eligible money brought in from outside India and held in a rupee account that is generally repatriable under RBI rules.
The important distinction is not the bank branch. It is the source of the money.
The usual process
Inform your bank
Tell the bank that your residential status has changed and ask which channel it accepts for redesignation.
Request conversion
Submit the bank's resident-to-NRO conversion request for your existing account.
Complete KYC
Provide the bank's required identity, overseas-status, and address documents.
Review linked services
Check cards, SIPs, EMIs, UPI, standing instructions, and other services tied to the old account status.
Open NRE separately
If you need an account for eligible foreign remittances, open a separate NRE account.
ICICI Bank's current form list includes a specific request to change an existing resident account to NRO, along with separate forms for opening an NRE or NRO account. SBI's current NRI FAQ similarly says an NRI cannot maintain a domestic account and that the existing resident account must be converted to NRO or closed.
Documents banks usually ask for
- IdentityA copy of your valid passport and passport-size photographs.
- Overseas statusYour visa, residence permit, work permit, or another document that establishes your status abroad.
- AddressProof of your current overseas address.
- Indian tax identityYour PAN details.
- Bank paperworkThe bank's account-conversion and KYC forms.
The exact list and submission method vary by bank. ICICI Bank's current document page, for example, asks customers to send an account-modification request with a self-attested copy of a valid passport using the channel stated on the form.
How long does it usually take?
RBI does not set one universal turnaround time for account redesignation. The timing depends on your bank, whether the paperwork is complete, whether additional KYC is required, and whether the bank must update cards, digital banking, or linked mandates.
Ask for the current processing estimate before submitting the request, keep copies of every document, and retain the acknowledgement or tracking number.
Missing documents or mismatched names and addresses can extend the process, so check the bank's current checklist carefully.
Common mistakes to avoid
- Leaving a resident savings account active after your residential status changes.
- Assuming a resident account can simply become NRE.
- Forgetting to review cards, SIPs, EMIs, UPI, or standing instructions.
- Mixing foreign income and Indian income without tracking the source.
- Sending incomplete or inconsistent KYC documents.
The easiest way to avoid delays is to treat the conversion as a status update across your banking relationships, not just a form-filling exercise.
What about returning to India later?
If you return to India with the intention of staying, RBI says NRO accounts may be redesignated as resident accounts. NRE accounts should be redesignated as resident accounts or transferred to RFC accounts, depending on the account holder's choice and eligibility. FCNR(B) deposits may continue until maturity if the holder wants that.
That is useful to know now because the account you choose today may need a second status change later.
Final word
If you have moved abroad, do not keep using an old resident savings account as if nothing changed. Redesignate it to NRO, open NRE separately if you need an eligible foreign-remittance account, and keep your documents ready. That keeps your banking aligned with your residential status and makes future repatriation easier too.
Convert the old resident account to NRO; open NRE separately for eligible foreign funds.
If your situation is unusual, check the current requirements with your bank or a qualified adviser before submitting the request.